LATEST COMMENTARY
FIVE THINGS TO KNOW
MCT READER PULSE · MCT-PULSE-2026-017
MCT READER SURVEY
Gaano ka nagtitiwala na tama ang ginagawa ng Kongreso sa budget ng bayan?
This is an informal survey of people who choose to participate. It is not a scientific or nationally representative sample.
ABOUT MISSING A HOUSE PAYMENT AND YOUR RIGHTS AS AN INSTALLMENT BUYER
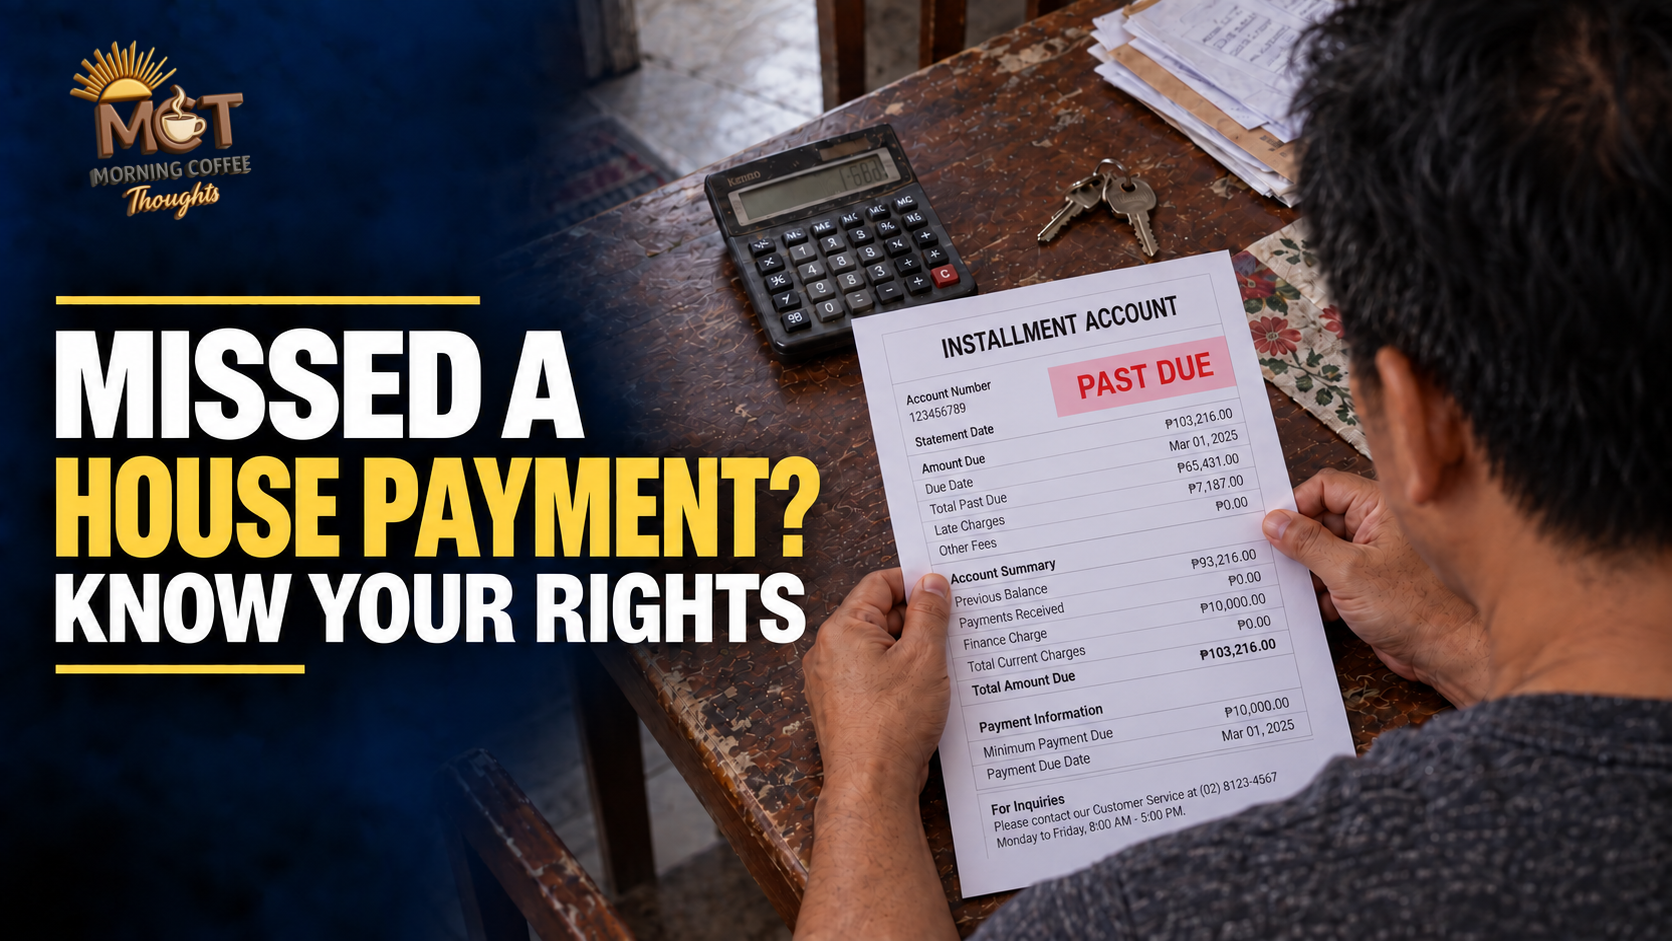
A missed house payment can leave a family wondering whether everything it has already paid will be lost. Before accepting a cancellation notice or signing away your claim, check the kind of agreement you have, how much you have paid, and which protections apply.
The Maceda Law, or Republic Act 6552, already gives covered installment buyers time to catch up and sets conditions for cancellation. Recent reports about Senator Francis Escudero’s proposal to strengthen the law have brought these rights back into the news. Buyers should understand the existing rules while the proposed changes move through Congress.
1
Check whether your agreement is covered
The Maceda Law protects buyers in covered real estate installment transactions, including residential condominium purchases. The law excludes industrial lots, commercial buildings and certain sales to agricultural tenants covered by the land reform laws it names.
Your contract and payment arrangement need to be checked carefully. Paying a seller through an installment sale and repaying a separate housing loan can involve different legal questions. A monthly payment alone does not establish which rights apply to your case.
Keep your contract, receipts, statement of account and any notices together. If someone says you have no rights because of a clause in the contract, ask for the legal basis. Contract terms that conflict with the protections in Sections 3 to 6 of the Maceda Law are void.
WHAT TO WATCH
Ask for a written explanation of your agreement’s coverage and the seller’s calculation of the installments you have paid. Have the contract reviewed if the answer is disputed.
2
The grace period depends on how much you have paid
For a covered buyer who has paid at least two years of installments, the law allows one month of grace for every year of installment payments made. During that earned period, the unpaid installments can be paid without additional interest. This right can be used only once in every five years of the contract and its extensions.
For example, three years of installment payments can earn three months of grace, subject to that limit on how often the right may be used. Buyers who have paid less than two years must receive a grace period of at least 60 days from the date the installment became due.
The law also includes down payments, deposits and options in computing the total number of installment payments made. Do not rely only on how long ago you signed the contract. Ask for the payment calculation and the exact date on which the applicable grace period ends.
WHAT TO WATCH
Confirm the payment record, due date, grace-period deadline and whether the earned grace right has already been used within the relevant five years.
3
Cancellation must follow the required process
For buyers who have paid at least two years of installments, cancellation carries a refund called the cash surrender value. It starts at 50 percent of total payments. After five years of installments, an additional five percentage points is added for each further year, up to a maximum of 90 percent.
As an illustration, a covered buyer with ₱600,000 in total payments and three years of installments would have a cash surrender value of ₱300,000. The actual payment record and applicable percentage still need to be checked.
For this group, actual cancellation requires both the passing of 30 days from the buyer’s receipt of a notice of cancellation or demand for rescission through a notarial act, and full payment of the cash surrender value. The seller cannot treat an ordinary collection message as a substitute for all those requirements.
For buyers below the two-year threshold, the seller must first allow the required grace period. If the buyer still fails to pay, cancellation can take place only after 30 days from receipt of the required notarial notice. Section 4 does not provide the same automatic 50 percent refund. Any other refund claim needs its own basis in the contract, the facts or another applicable law.
WHAT TO WATCH
Keep the notice and proof of when you received it. Check its form, the cancellation date and, when applicable, whether the full required refund has actually been paid.
4
You may still have options before actual cancellation
The law allows a covered buyer to reinstate the contract by updating the account during the grace period and before actual cancellation. It also allows the buyer to sell or assign the rights to another person during that period. The deed of sale or assignment must be done through a notarial act.
These options can help a buyer who needs to catch up or can no longer continue the purchase. They still require proper documents and timely action. An informal agreement with another person should not be treated as a completed transfer of the buyer’s rights.
Ask the seller for a written statement of the amount needed to update the account. If you want to transfer your rights, get the documents reviewed before accepting money or signing. Keep copies of the agreement and proof of payment so there is a clear record of what each person has agreed to do.
WHAT TO WATCH
Follow the deadline for updating the account or completing an assignment. Get written confirmation of any reinstatement instead of relying on a verbal promise.
5
Proposed protections should be kept separate from existing rights
Reports published on October 1 and 2 describe Escudero’s proposal to penalize sellers for delayed refunds and delayed title transfers. The reported proposal includes a monthly penalty for late refunds and a deadline for transferring ownership after full payment.
Those reported additions are proposals. Buyers should not demand a newly proposed penalty as though it were already an enforceable provision of the existing Maceda Law. Likewise, the grace periods and basic cash surrender rules discussed above are protections already written into the current law.
If a seller has missed a promise or failed to follow the existing cancellation rules, the buyer can have that conduct reviewed under the law and contract that apply now. Waiting for Congress to amend the law should not replace checking the rights and deadlines already available.
WHAT TO WATCH
Follow the official bill text and its progress through Congress. Any final version needs to be checked for approval, effectivity and the transactions it covers before buyers rely on its new provisions.
BOTTOM LINE
If you miss an installment, get your documents together and ask for the account calculation and deadlines in writing. The Maceda Law provides protections for covered buyers, but the payment history and cancellation process have to be checked. Understanding those details can help a family respond before it signs away a claim or lets a deadline pass.
GOOGLE PREFERRED SOURCES
FOLLOW MCT ON GOOGLE
Google’s Preferred Sources feature lets you choose publications you want Google to prioritize for you. Select “Add to Preferred Sources” to make MCT easier to find in Top Stories and other eligible Google results. This does not subscribe you to email.