MCT CASE TRACKERTracking Sara Duterte’s impeachmentHearings, documents and disputed issues.Follow the trial → MCT CASE TRACKERTracking Rodrigo Duterte’s ICC caseCourt records, hearing dates and sourced notes.Follow the case →

LATEST COMMENTARY

View all commentary →

FIVE THINGS TO KNOW

Afternoon6-minute read

ABOUT THE OVP’S 2027 BUDGET AFTER A 16-MINUTE SENATE HEARING

The Office of the Vice President’s proposed budget moved through a Senate panel today in 16 minutes. Vice President Sara Duterte was absent; her chief of staff answered for the office. Yesterday’s MCT explainer looked at parliamentary courtesy. Today’s question is what that short hearing actually did to the spending plan, and what it left for the Senate to examine.

Read the explainer →
Afternoon6-minute read

ABOUT THE EDSA BUSWAY’S 2027 BUDGET GAP

The Department of Transportation is again asking Congress to fund the EDSA Busway. Its original ₱1.756 billion request received zero in the administration’s proposed 2027 National Expenditure Program. A House budget panel later inserted ₱75 million. Those two statements describe different stages of the same budget process. Neither tells us yet what Congress will finally approve.

Read the explainer →
Afternoon7-minute read

ABOUT DECLARING AN AMBASSADOR PERSONA NON GRATA

Several lawmakers want Chinese Ambassador Jing Quan sent home. The Chinese Embassy has challenged them to follow through. That exchange leaves an ordinary reader with a reasonable question: if our own officials say an ambassador should leave, why is he still here?

Read the explainer →
7:23 AM5-minute read

ABOUT LINO CAYETANO AND THE CHANGE AT THE PCO

President Ferdinand Marcos Jr. announced on October 11 that Lino Cayetano would replace Dave Gomez at the Presidential Communications Office. He said Gomez had been bypassed by the Commission on Appointments and that the change would be formalized when they returned from Singapore.

Read the explainer →
6:10 PM4-minute read

ABOUT THE DISPUTE OVER CHANGING THE ORDER OF IMPEACHMENT WITNESSES

The argument at Thursday’s impeachment hearing was about which witness the prosecution could present next. It began with an absent lawyer and became a dispute over preparation and notice. Understanding the exchange helps explain why a courtroom can pause even when the parties, documents and another potential witness are already in the building.

Read the explainer →
3:01 PM3-minute read

ABOUT MARK VILLAR’S MOVE TO THE SENATE MAJORITY

Senator Mark Villar has formally left the Senate minority and joined the majority. The October 8 move strengthens the bloc supporting the chamber’s leadership and gives Villar two significant positions. Its implications for Sara Duterte’s impeachment trial, however, require more than counting political allies.

Read the explainer →
9:56 AM4-minute read

ABOUT THE MANAGER’S CHECKS AND THE QUESTIONS OVER SARA DUTERTE’S SALN

A bank balance can fall even when the value represented by the money has not disappeared. That distinction sits behind the prosecution’s questions about manager’s checks in Sara Duterte’s impeachment trial. To understand the October 7 testimony, we need to follow the instrument, the person entitled to its value and the declaration of assets for the relevant year.

Read the explainer →
9:08 PM3-minute read

ABOUT WHAT COA’S REJECTION OF THE OVP APPEAL MEANS

COA has rejected the request to reconsider the ₱73.287-million disallowance involving the Office of the Vice President’s December 2022 confidential expenses. The October 5 resolution became public on October 7. Its significance is easier to understand when the amount, the audit finding and the available legal remedies are kept separate.

Read the explainer →
7:47 AM3-minute read

ABOUT WHAT BANK SECRECY PROTECTS IN AN IMPEACHMENT TRIAL

The arguments over bank records in Sara Duterte’s impeachment trial involve several protections. The privacy of a peso deposit, the protection of a foreign-currency deposit, and the confidentiality of a report sent to the AMLC come from different rules. Understanding those differences helps explain what the court has allowed and what remains in dispute.

Read the explainer →
8:43 AM8-minute read

ABOUT THE AMLC RECORDS IN SARA DUTERTE’S IMPEACHMENT TRIAL

₱4.4 billion is a figure that can dominate a conversation before anyone asks what it counts. AMLC Executive Director Ronel Buenaventura presented that approximate total in the Senate impeachment court on October 5, covering reported transactions involving Vice President Sara Duterte and her husband, Manases Carpio. He also explained that a bank correction had reduced the earlier figure of ₱6.7 billion.

Read the explainer →
6:44 PM5-minute read

ABOUT THE COINS.PH CASH-IN RESTRICTION AND WHAT USERS SHOULD CHECK

If you use Coins.ph to receive money or pay bills, a failed cash-in can disrupt plans for the day. Coins.ph has announced that some incoming peso services are temporarily unavailable following a BSP directive to improve its internal controls. Its advisory also identifies services that existing customers can still use.

Read the explainer →
12:00 PM5-minute read

ABOUT THE PROPOSED RULES ON SECONDHAND PHONES

A secondhand phone can put a useful device within reach of someone who cannot afford a new one. The problem comes when the buyer has no clear information about where it came from, what condition it is in, or who will fix it if it fails.

Read the explainer →
8:35 PM6-minute read

ABOUT THE SUPREME COURT’S DECISION ON THE IMPEACHMENT VOTE THRESHOLD

The Supreme Court dismissed three petitions on September 30 challenging how the Senate impeachment court would count the votes needed to convict Vice President Sara Duterte. The dismissal leaves the Senate’s September 23 ruling in place, but it needs to be read carefully. A case can be dismissed because it does not meet the requirements for the Court to hear it, without settling whether the challenged action is constitutional.

Read the explainer →
6:12 AM6-minute read

ABOUT WHAT BASTE DUTERTE SHOULD HAVE CHECKED AS MAYOR

Davao City Mayor Sebastian “Baste” Duterte told the Senate impeachment court on September 29 that he had been unfamiliar with GenCorp Industries Inc. before it came up in the proceedings. He also said he did not know about Vice President Sara Duterte’s declared business interest in the company.

Read the explainer →
10:45 PM7-minute read

ABOUT THE OCTOBER WATER-RATE INCREASES

Metro Manila households served by Maynilad and Manila Water will see slightly higher water charges beginning October 1. The announced increases are small for many residential customers, but the figures vary by concessionaire and consumption level. That makes it easy to misunderstand a notice expressed only in centavos per cubic meter.

Read the explainer →
7:21 AM6-minute read

ABOUT THE NOTE HANDED TO GIBO TEODORO IN SEOUL

Defense Secretary Gilberto “Gibo” Teodoro Jr. was answering questions at the Seoul Defense Dialogue on September 8 when a man handed him a note. He read it aloud, challenged its rejection of the 2016 South China Sea ruling and objected to being interrupted that way.

Read the explainer →
9:55 AM8-minute read

ABOUT EL NIÑO AND PREPARING FOR LESS RAIN

It can be raining outside while PAGASA warns about El Niño. That can sound confusing when the immediate problem is a wet road or a flooded field. The two warnings describe different periods: the weather happening now and the rainfall conditions that may develop over the coming months.

Read the explainer →
5:30 AM8-minute read

ABOUT THE NEW ARREST WARRANTS AGAINST ZALDY CO, MARTIN ROMUALDEZ AND TWO OTHERS

The Sandiganbayan has ordered the arrest of Zaldy Co, Martin Romualdez and two other accused in the plunder case filed on September 7. By Monday evening, authorities had served Romualdez's warrant and carried out booking procedures at Cardinal Santos Medical Center in San Juan. His arrest is a confirmed development; it does not establish that his three co-accused are also in custody.

Read the explainer →
3:15 PM8-minute read

ABOUT THE PLUNDER CASE AGAINST MARTIN ROMUALDEZ

The Office of the Ombudsman filed a plunder case against former House Speaker Martin Romualdez at the Sandiganbayan on September 7 over his alleged involvement in flood-control kickbacks. The accusations have now reached the court that will handle the criminal case. Romualdez denies wrongdoing and remains presumed innocent.

Read the explainer →
1:18 PM7-minute read

ABOUT THE NEW SWS POVERTY NUMBERS

Self-rated poverty and food poverty declined in June, but the figures also show how many Filipino families remain under pressure and why lower household budgets do not necessarily mean life became cheaper.

Read the explainer →
2:02 PM11-minute read

ABOUT THE CHILDREN'S SOCIAL MEDIA SAFETY ACT

House Bill No. 9965 would bar children below 13 from having social media accounts, require parental consent for users aged 13 to 17, regulate platform algorithms, and impose fines reaching P50 million. It is still being deliberated in the House.

Read the explainer →
12:02 PM7-minute read

ABOUT THE SEALED BIR BOX

Marcos authorized the BIR to comply with the Senate subpoena. That did not open the records to the public or prove the unexplained-wealth allegation.

Read the explainer →

MCT READER PULSE · MCT-PULSE-2026-015

MCT READER SURVEY

Dapat bang ideklara ng pamahalaan ng Pilipinas na persona non grata si Chinese Ambassador Jing Quan at hilingin sa China na pauwiin siya?

Answer the survey →

This is an informal survey of people who choose to participate. It is not a scientific or nationally representative sample.

View previous survey results →
September 6, 2026 · 10:15 AM8-minute read

ABOUT RECEIVING A BIR AUDIT NOTICE

The authority, records and questions to check under the consolidated audit rules.

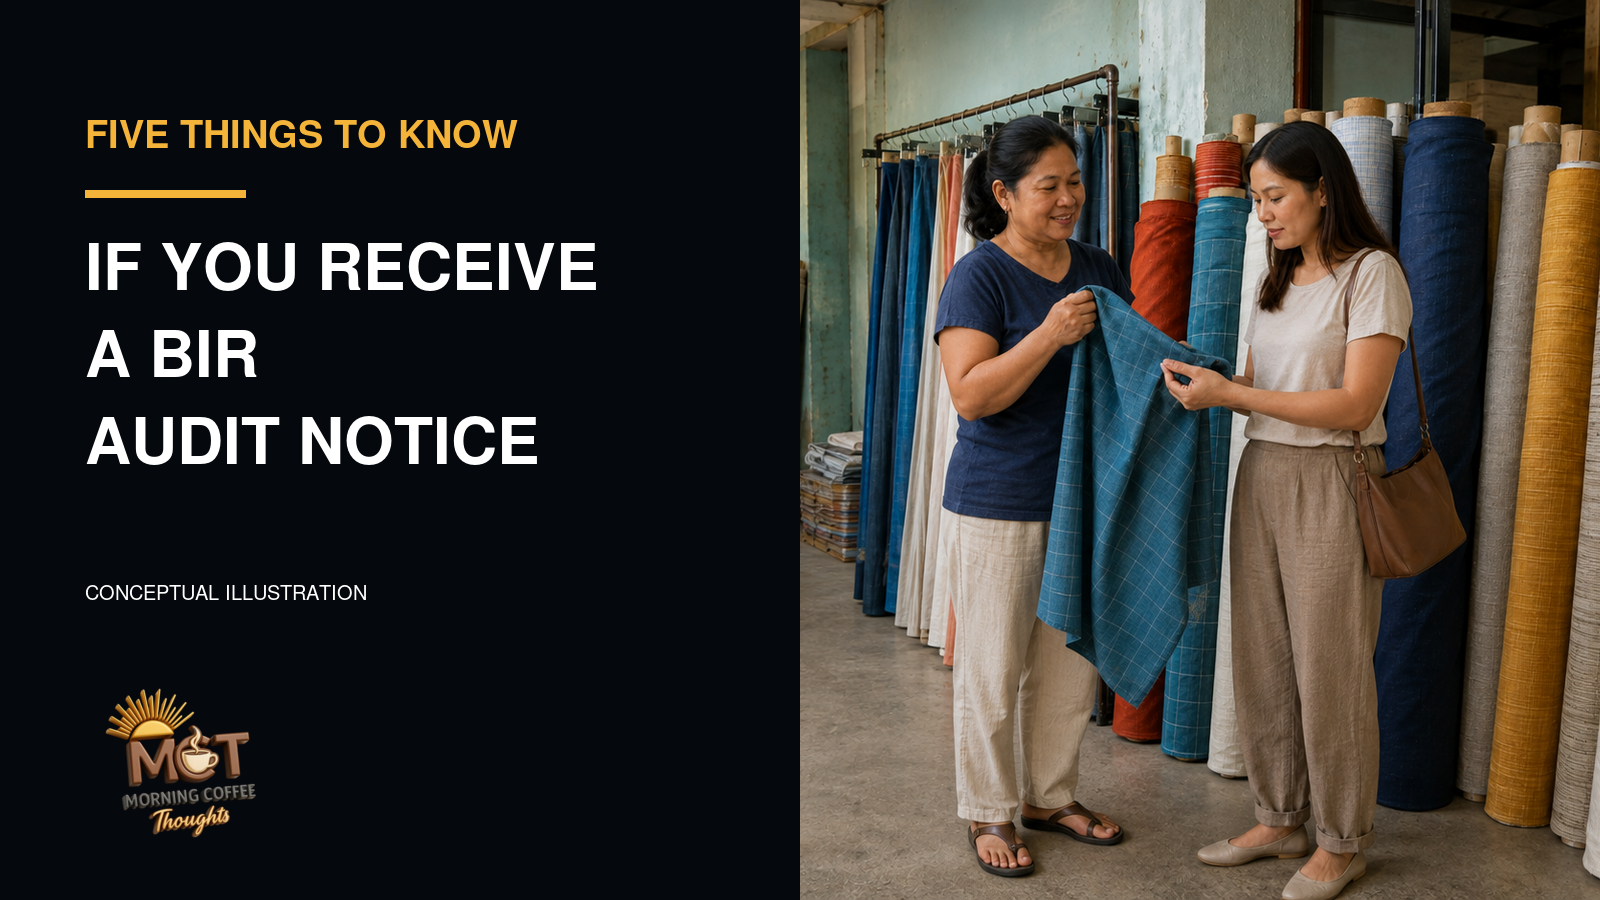
Conceptual illustration of a shopkeeper and customer handling fabric in a Philippine textile shop. Fictional people; not an actual BIR inspection.
Conceptual illustration made by MCT with AI, September 6, 2026. Fictional people and shop; not a photograph of an actual tax audit.

A letter from the Bureau of Internal Revenue can send a small-business owner straight to the filing cabinet, then to the accountant. Which records are being requested? Which tax year is involved? Has the same period already been examined? These are sensible questions to ask before making assumptions about what the letter means.

The BIR's consolidated audit program, contained in Revenue Memorandum Order 22-2026, was issued in August and received renewed news coverage this weekend. It brings together rules on selecting cases, assigning examiners, requesting records and reviewing findings. Its promises of more consistent treatment need to show up in the actual handling of taxpayers' cases. Here are five places to look when reading a notice and discussing it with the professional helping you respond.
1

IDENTIFY WHAT THE NOTICE ACTUALLY AUTHORIZES

Start with the document itself. An electronic Letter of Authority, or eLA, authorizes a tax examination within its stated scope. Other authorized instruments, including a Tax Verification Notice or Mission Order, serve their own purposes under the applicable rules. A request to examine records should not be confused with a final determination of additional tax due.

That difference affects what you need to prepare. At the examination stage, the work concerns checking records and explaining discrepancies. If the BIR later issues an assessment, the taxpayer is dealing with claimed tax liabilities and the procedures for responding to them. Treating every letter as an identical demand can lead to the wrong response.

Read the taxpayer details, issuing office, document number and stated purpose with your accountant or tax adviser. Keep a copy of the entire notice and a record of when it was received. Those basic details help establish which communication you are answering and allow someone reviewing the case later to follow its sequence.

If something appears inconsistent, seek verification through the responsible BIR office. A question about authority needs to be addressed promptly; it is not a reason to leave the correspondence unattended.

WHAT TO WATCH

Check whether the next request or notice corresponds to the authority already served. Any unexplained change in the purpose or issuing office deserves clarification before you assume it is the same step in the case.

2

CHECK WHY YOUR BUSINESS WAS SELECTED

The program distinguishes mandatory cases from priority cases. Some audits or verifications arise because a transaction or application requires checking, including certain tax-clearance, refund and credit cases. Others are selected using risk indicators and information available to the BIR. These categories explain why a case may begin; they do not settle what the examination will find.

For priority cases, the order generally uses the BIR's computer systems to select taxpayers using defined criteria and verifiable data, subject to the commissioner's approval. Mandatory cases follow a different selection route. It would be misleading to say that a computer now chooses every taxpayer who will be examined, or that human recommendations have disappeared.

An unexplained difference between records can require examination without proving dishonesty. Think of a business asked to reconcile figures from its returns with information supplied by other parties: the next useful task is to identify the records behind each figure and explain any difference. That example is a reason to prepare the evidence, not an assurance that every discrepancy is harmless.

Ask the person helping you respond to identify the stated basis for selection and how it relates to your records. The answer should be more specific than a general claim that everyone is now being audited.

WHAT TO WATCH

Look for a concrete selection basis and the records supporting any claimed discrepancy. Those will help you focus your response on the actual question being examined.

3

CHECK THE TAX YEAR AND SCOPE, INCLUDING ANY REPLACEMENT AUTHORITY

The single-instance audit framework generally provides one eLA for a taxpayer's taxable year covering the applicable internal revenue taxes, subject to the rules' exceptions. It aims to avoid splitting examinations for the same year across separate authorities. The word “one” still needs careful reading: the rules allow documents to be replaced or combined so an existing examination can lawfully continue.

A replacement eLA, for example, can allow an existing examination to continue when the assigned officers change. A consolidated eLA can bring earlier authorities for the same taxpayer and year together. Receiving another document therefore does not, by itself, prove an improper duplicate audit.

Compare the old and new documents with your adviser. Which year and taxes are covered? Who is authorized to handle the case? Does the letter explain the replacement or consolidation? Keeping these documents together makes that comparison possible without relying on someone's memory of an earlier visit.

The reverse assumption is risky too. A previous examination should not be treated as permission to disregard all later correspondence. Where the scope or authority is disputed, the response needs to address the specific document and the rules that apply to it.

WHAT TO WATCH

Watch for a written notice identifying the authority being replaced or consolidated. Clarify any unexplained difference in years or tax types rather than assuming the new letter changes everything.

4

ORGANIZE THE RECORDS AND PUT THE ARRANGEMENTS IN WRITING

An audit can take time away from running a shop, serving clients or managing deliveries. The consolidated program retains a standard requirements checklist and provides a form addressing the audit venue and an authorized representative. Read those documents carefully with the person assisting you, especially if your books and supporting records are extensive.

The rules allow arrangements for examining records at the appropriate BIR office or the taxpayer's principal place of business, subject to coordination and the applicable conditions. The choice is not unlimited. If a valid subpoena requires the records, they must go to the BIR office specified in that order.

Begin with an organized inventory of what has been requested, what has been supplied and what still needs clarification. Keep copies of submissions and acknowledgments. If the owner and accountant are both communicating with examiners, make sure each knows what the other has already provided; inconsistent or incomplete handovers make a response harder to reconstruct.

Do not assume a generic online deadline fits every document. The order sets a sequence of notices for missing records, and continued noncompliance can escalate. Have the actual notice, service date and applicable response period checked promptly instead of waiting for the next letter.

WHAT TO WATCH

Track the next submission date and any written follow-up about missing records. A clear record of requests and responses helps prevent uncertainty over whether an item was supplied or remains outstanding.

5

THE AUDITORS' WORK CAN ALSO BE CHECKED

The program provides for Revalida, described as an audit of auditors. This covers review of findings, computations and assessment documents, and the order calls for separate detailed guidelines. It sets out an accountability mechanism on paper; it does not establish that every taxpayer has already benefited from such a review.

For someone facing a disputed finding, the practical question remains specific: which transaction, document or calculation supports it? Ask your adviser to work through the written explanation alongside your own records. A broad promise of fairness cannot answer whether a particular amount has been calculated correctly.

The BIR's own documentation should allow the case to be followed from the authority and requests through the findings and subsequent action. Keeping your side of that record organized helps an adviser identify what was submitted, what was discussed and where disagreement remains.

Auditor accountability and a taxpayer's response obligations run alongside each other. An announced review mechanism should not be treated as an automatic appeal, a promise to cancel an assessment or a reason to miss a response deadline. If a finding is contested, obtain advice on the procedure and timing that apply to that particular notice.

WHAT TO WATCH

Check the BIR's separate Revalida guidance and, in your own case, the written findings and response requirements. Those are more useful than assuming the reform has already corrected a disputed assessment.

BOTTOM LINE

You do not need to memorize every BIR abbreviation to begin responding sensibly. You need the complete notice, the relevant records and a clear account of what has happened so far. Take those to the accountant or tax adviser helping you, and ask concrete questions about authority, scope and the next response date. The same care should be expected from the BIR: requests that can be understood, findings supported by records and procedures followed consistently. A new audit program will earn confidence through those everyday dealings with taxpayers.

GOOGLE PREFERRED SOURCES

FOLLOW MCT ON GOOGLE

Google’s Preferred Sources feature lets you choose publications you want Google to prioritize for you. Select “Add to Preferred Sources” to make MCT easier to find in Top Stories and other eligible Google results. This does not subscribe you to email.

← Back to MCT home

SUPPORT MCT

HELP KEEP INDEPENDENT POLITICAL WRITING GOING.

Morning Coffee Thoughts is reader-supported. Contributions help pay for research tools, hosting, and the work required to verify and explain each development.

Monthly PayPal subscription — choose your support amount.Subscribe monthly through PayPal

PayPal automatically charges your chosen amount every month until you cancel the subscription in PayPal.

Send support through GCash or Maya0969 314 4839